
Market Commentary – October 2026
10/11/2026
Key Themes Driving Currency Markets
Dire Straits
October brought a sharp escalation in the Middle East conflict, as the US and Iran exchanged fire and record number of tankers came under attack according to data from Kpler. Energy flows through the Strait of Hormuz collapsed to 2.9 million barrels per day on 11 October from 20.8 million just three days earlier, driving Brent crude past $110bbl by mid-month. Late-month reports that Iran’s leadership was discussing conditions to end the war, with Qatar and Pakistan mediating, trimmed oil from its highs, but Brent still ended the month well above its September close.
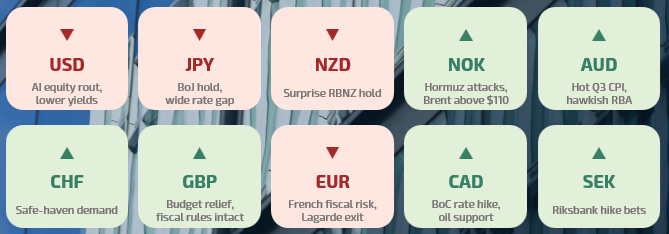
Energy exposure was the clearest dividing line in G10 FX. NOK was the standout performer on an elevated energy risk premium and a tight European gas market. CAD was supported by the oil move as well as the BoC hiking in response to Middle East-linked inflation pressures. The ECB stayed on hold as energy prices and French fiscal chaos undermined the bloc’s growth outlook.
AI Trade Falters on Earnings
The Nasdaq Composite set an all-time closing high on 6 October before lacklustre tech earnings removed some of the AI trade’s sheen. Doubts over whether data-centre operators can earn enough to service their debts spread into credit markets, while rising Chinese chip competition added to the pressure. Faltering sentiment contributed to a mid-month rout in chip stocks and the dollar slid as investors rotated out of US tech equities. Further selling occurred after disappointing earnings results from Intel and Amazon raised concerns over the sustainability of the AI capex cycle. With AI capex a key pillar of US growth, the equity selloff pulled Treasury yields lower, eroded dollar support, and raised concerns about “hot money” flows driving the dollar.
FOMC Holds as Hawks Dissent
The FOMC left its policy rate unchanged at its October policy meeting, with Governor Cook and Cleveland Fed President Hammack dissenting in favour of a 25bp hike. The surprise dissent from Cook places pressure on Chair Warsh to back up his hawkish communique by delivering a hike at the December FOMC meeting. Warsh characterized the US growth outlook as “strong” and stated he was “unwilling and unable” to describe financial conditions as tight. Warsh also announced that the FOMC will be moving to 7 policy rate meetings in 2027 and just 6 rate meetings in 2028. The announcement generated further uncertainty into the US rate path, as a reduced number of “live” meetings raises the stakes for each hike or hold going forward. The USD saw marginal gains in the aftermath of the meeting but those were quickly erased by the late-October tech sell-off.
Elsewhere, the BoJ held rates again but signalled further hikes are on the horizon. The yen recovered some ground in response to the hawkish forward guidance, but JPY continued to weaken from its post-intervention peak as the yen’s rate disadvantage went unaddressed. The ECB also left its policy rate unchanged in October as policymakers balanced elevated inflation against faltering growth and rising fiscal pressures.
N.B.: This summary includes market events and currency movements up to end-of-October.
Please click here for additional information, including risk disclosures.